
What Happens When A Louisiana Insurer Denies Wind Damage?
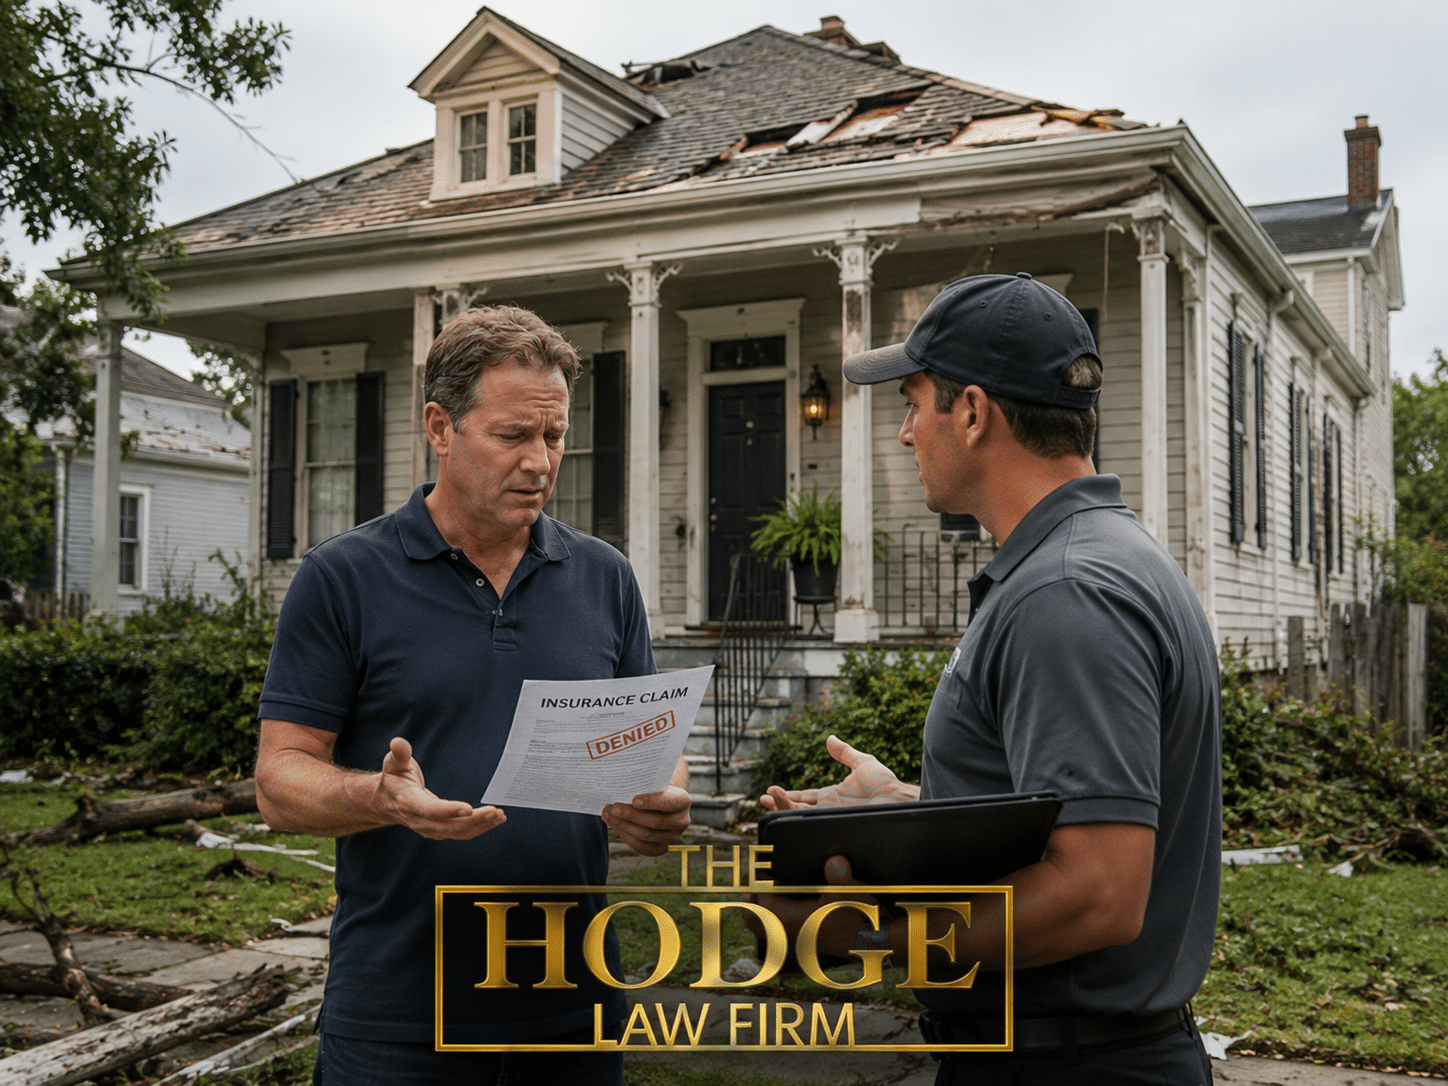
A hurricane or strong windstorm can turn life upside down in just a few hours. High winds might rip shingles off your roof, break windows, damage siding, knock down fences, and leave your home or business open to water damage. After the storm, most people work to protect their property, take photos of the damage, and file an insurance claim. They trust that the insurance company they have paid for years will honor their policy and help cover the repairs.
Sadly, many Louisiana property owners are surprised when their insurance company denies their claim or refuses to pay for much of the wind damage. This can leave homeowners and business owners worried about how they will afford repairs and keep up with other bills. It adds even more stress during an already difficult time.
At The Hodge Law Firm, we help homeowners and business owners with tough insurance disputes after hurricanes and windstorms. We know how insurance companies handle these claims, and we work to make sure they meet their responsibilities. If your wind damage claim was denied, remember that the insurance company’s decision is not always final.
A Claim Denial Does Not Always Mean Your Loss Is Uncovered
Many property owners assume that once an insurance company denies a claim, there is nothing more they can do. Many people think that if their insurance company denies a claim, there is nothing else they can do. That is not true. A denial letter only shows the insurance company’s view after their investigation and reading of the policy. It does not always mean the decision is right. It can be difficult to understand without careful review. In addition, insurance adjusters sometimes make decisions based on incomplete inspections or information that does not accurately reflect the true condition of the property.
Before you accept a denial, make sure you know why your claim was rejected and whether the insurance company looked at all the evidence. Many denied claims should be reviewed again, especially when there is a lot of wind damage.
Why Louisiana Insurance Companies Deny Wind Damage Claims
Insurance companies may deny wind damage claims for several different reasons. Some denials involve legitimate coverage disputes, while others may result from incomplete investigations or narrow interpretations of policy language.
Some of the more common reasons insurers deny wind damage claims include:
- Alleging the damage existed before the storm.
- Claiming the roof failed because of age or deterioration.
- Arguing the damage resulted from poor maintenance.
- Contending that water, rather than wind, caused the loss.
- Stating that the damage does not exceed the deductible.
- Relying on policy exclusions to deny coverage.
- Claiming there is insufficient evidence connecting the damage to the storm.
Every denial should be evaluated based on the specific facts, the policy language, and the evidence supporting the claim.
Wind Damage Can Be More Extensive Than It First Appears
One reason insurance disputes frequently occur is that wind damage is often far more extensive than what is visible during an initial inspection. High winds can compromise roofing systems without immediately creating large openings. Shingles may become loosened, flashing may separate, and underlying materials may sustain damage that is not visible from the ground.
As time passes, these hidden problems can allow moisture to enter the building, resulting in damaged insulation, stained ceilings, warped flooring, mold growth, and structural deterioration. By the time these issues become obvious, the insurance company may argue that the additional damage developed after the inspection or was caused by something other than the hurricane.
A thorough evaluation should consider not only the immediately visible damage but also the ways hurricane-force winds may have affected the overall integrity of the structure.
Wind Versus Water Is A Common Source Of Disputes
One of the most common issues in Louisiana hurricane claims involves determining whether damage resulted from wind or water. This distinction can have a significant impact because insurance policies often provide different coverage for wind damage than they do for flood-related losses.
Insurance companies sometimes argue that water caused the majority of the damage, even when wind first compromised the structure. For example, high winds may remove shingles or damage roofing materials, allowing rain to enter the building. If the insurer focuses only on the resulting water damage without considering how the wind created the opening, disputes frequently arise.
Determining the sequence of events is often one of the most important parts of evaluating a denied wind damage claim.
Louisiana Law Requires Insurance Companies To Act In Good Faith
Louisiana law provides important protections for insurance policyholders. Insurance companies are generally expected to adjust claims promptly, conduct reasonable investigations, and deal fairly with their insureds.
Louisiana Revised Statute 22:1892 establishes duties that insurers owe to policyholders and may provide remedies when an insurance company acts arbitrarily, capriciously, or without probable cause in handling a claim. While not every denied claim constitutes bad faith, these statutes recognize that insurers have obligations beyond simply issuing coverage decisions.
If an insurance company fails to properly investigate wind damage, ignores available evidence, or unreasonably delays payment, additional legal issues may arise beyond the underlying property damage claim.
What Property Owners Should Do After Receiving A Denial Letter
Receiving a denial letter can be discouraging, but it is important not to assume the claim is over. The steps you take immediately afterward may significantly affect your ability to pursue additional compensation.
Property owners should consider:
- Carefully reviewing the denial letter.
- Saving every communication received from the insurance company.
- Photographing all damaged areas before additional deterioration occurs.
- Obtaining repair estimates from qualified contractors.
- Keeping receipts for emergency repairs.
- Preserving damaged building materials when practical.
- Consulting an attorney before accepting the denial as final.
These actions can help preserve important evidence and provide a clearer understanding of the issues surrounding the claim.
How The Hodge Law Firm Helps Challenge Denied Wind Damage Claims
Insurance companies have adjusters, engineers, consultants, and attorneys working to protect their financial interests. Property owners deserve experienced legal representation focused solely on protecting theirs.
At The Hodge Law Firm, we carefully review the insurance policy, analyze the reasons for the denial, evaluate inspection reports, and examine the available evidence. We work to identify whether damage was overlooked, whether policy language has been misapplied, or whether the insurance company failed to conduct a reasonable investigation.
Many claims can be resolved through additional negotiations once deficiencies in the insurer’s evaluation are identified. When an insurance company refuses to honor its obligations, however, litigation may become necessary. Our attorneys are prepared to aggressively pursue legal action when appropriate to help clients obtain the compensation they deserve.
Why Waiting Too Long Can Hurt Your Claim
Some property owners spend months attempting to convince the insurance company to reconsider its decision before seeking legal guidance. During that time, important evidence may deteriorate, repairs may become more expensive, and memories regarding the condition of the property immediately after the storm may fade.
Insurance policies and Louisiana law may also impose deadlines that affect your rights. Seeking legal guidance promptly allows your claim to be evaluated while evidence is still available and before unnecessary delays create additional obstacles.
Early action also provides an opportunity to determine whether the insurance company has fulfilled its legal obligations throughout the claims process.
Frequently Asked Questions About Denied Louisiana Wind Damage Claims
Can I Dispute A Denied Wind Damage Claim?
Yes. Many denied claims can be challenged after a careful review of the insurance policy, inspection reports, and evidence supporting the loss.
What If The Insurance Company Says My Roof Was Already Old?
An older roof can still sustain covered wind damage. The age of the roof does not automatically eliminate coverage under an insurance policy.
Should I Obtain My Own Contractor’s Estimate?
Independent repair estimates often provide valuable information regarding the actual scope and cost of repairs and may identify damage that was overlooked during the insurance inspection.
Can Hidden Wind Damage Be Discovered Later?
Yes. Some forms of wind damage become apparent only after repairs begin or moisture intrusion develops over time.
Does Every Denied Claim Mean The Insurance Company Acted In Bad Faith?
No. A denied claim does not automatically establish bad faith. However, if the insurer failed to investigate the claim reasonably or acted unfairly during the claims process, additional legal remedies may be available.
When Should I Contact An Attorney?
It is often beneficial to seek legal guidance soon after receiving a denial letter so the claim can be evaluated before important evidence is lost or additional deadlines arise.
Contact The Hodge Law Firm For A Complimentary Consultation
If your Louisiana wind damage claim has been denied, you do not have to accept the insurance company’s decision without understanding your legal rights. The Hodge Law Firm represents homeowners and business owners in insurance disputes and is committed to holding insurance companies accountable when they fail to honor the policies they issued.
Call the wind damage attorney at The Hodge Law Firm today at 409-762-5000 for a free consultation.
We Hold Insurance Companies Accountable.


